
By Guest Blogger. Any opinions expressed are those of the author(s), and do not necessarily reflect the views of Iraq Business News.
Tomorrow, September 30th, 2026, the last United States troops will have officially left Iraq, ending a military presence that began with the 2003 invasion. It is a genuine historical milestone. Iraqi Prime Minister Ali al-Zaidi has described the withdrawal deadline as "fixed and final." The Council of Ministers has declared a four-day public holiday in state institutions from Wednesday September 30th through Saturday October 3rd, resuming work on Sunday October 4th, an official celebration of what it is calling "Sovereignty Days".
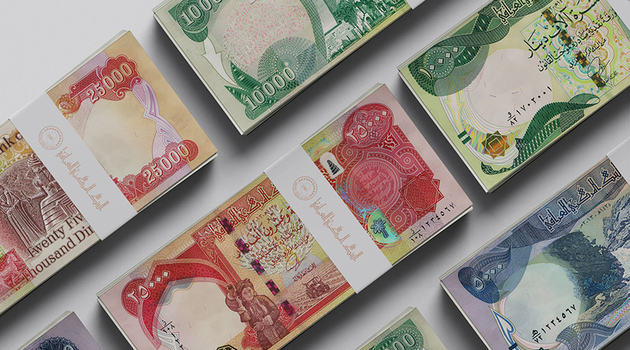
So: will the Iraqi dinar revalue (RV), as predicted by many on dinar speculation forums?
No. And the reasons why are worth understanding clearly, because the forums have been building toward this date for months.
What the Forums Have Been Saying
The dinar speculation community has treated September 30th as a trigger date for an imminent revaluation; the logic being that once American troops leave, Iraq reclaims full monetary sovereignty, and the Central Bank of Iraq (CBI) is then free to revalue the dinar. One post this week declared that "for most of the past 23 years, the IQD has traded in a country with American soldiers on its soil" and implied, without stating directly, that their departure changes the exchange rate picture. Another forum contributor described the four-day government shutdown as "a clean window."
This argument fails at almost every level, but it is worth addressing seriously, because it recycles a genuinely important piece of news -- the troop withdrawal -- and attaches a monetary conclusion that the news does not support.
Sovereignty and Monetary Policy Are Different Things
Iraq has had a functioning, independent central bank since 1947. The Central Bank of Iraq, established under CBI Law No. 56 of 2004, is legally independent of the government and has sole authority over monetary policy, including the exchange rate. American troops being stationed in Iraq did not give Washington control of the CBI's exchange rate policy, and their departure does not transfer any new authority to Baghdad. That authority has always resided in Baghdad.
The dinar's exchange rate of 1,310 IQD per US dollar was set by the CBI in February 2023 and has remained unchanged since. It was not imposed by Washington. It was not contingent on the presence of foreign troops. And it will not automatically change because those troops have left.
What the Exchange Rate Is Actually Doing
The parallel market rate (i.e. the rate at which Iraqis actually buy and sell dollars outside the official banking system) tells a different story to the one the forums are telling. The dollar is recently trading around 158,000 dinars per $100 in Baghdad's parallel exchanges, against buying rates of 157,000. The CBI's official peg sits at 131,000 dinars per $100. That is a gap of over 20 percent.
A market pricing in an imminent dramatic revaluation would be moving in the opposite direction. The parallel market premium reflects liquidity constraints, uncertainty, and demand for dollars outside the formal banking system, not confidence in an approaching windfall for dinar holders.
The CBI Has Said So, Repeatedly
This is not a matter of reading between lines. The Central Bank of Iraq has issued a formal public statement as recently as August 26 -- just over a month ago -- confirming that reports of new currency being printed with zeros removed were "not based on any official source," and setting out clearly that any future currency restructuring would require "multiple legal, regulatory and technical stages" before implementation, announced through official channels with "an appropriate transition period." A second CBI statement followed on September 5, specifically rejecting rumours of a rate change to 1,460 IQD per dollar.
The CBI does not govern by forum post. It will not announce a revaluation during a four-day public holiday. Ten days before Sovereignty Day, on September 19, the CBI published a formal statement on foreign reserve adequacy addressing the parallel market premium directly. It confirmed that Iraq's foreign reserves are sufficient to meet all demand for foreign currency, and stated plainly that the rise in the parallel market rate "is due to speculation in the markets, expectations, and the misuse of the geopolitical situation in the region to disrupt economic and financial conditions by some who benefit from this state of affairs." It called on citizens to rely exclusively on official CBI communications and not to follow news from unverified sources.
When a central bank uses the word "speculation" to describe what is driving its currency's parallel market rate ten days before the date forums are calling an RV trigger, that is the institution's answer to the forums, even if the forums are not the intended audience.
What September 30 Actually Means
The end of the US military mission in Iraq is significant news for Iraq as a country. It is the conclusion of a 23-year presence that reshaped the country's politics, economy and society. US Defense Secretary Pete Hegseth wrote on X in July that "a secure Iraq opens the door to strong commercial and defense cooperation," language about bilateral economic partnership, not monetary independence from a constraint that never existed in the form the forums describe.
For dinar holders watching the forums this week, the framing will be seductive: something historic is happening, the forums are excited, and the moment feels significant. That feeling is not evidence. Iraq has had many historically significant moments since 2003 -- elections, the defeat of ISIS, changes of government, oil production milestones -- and the dinar's exchange rate has remained range-bound throughout.
Sovereignty Day is a genuine occasion for Iraq. It is not a currency event.
The Bottom Line
The Iraqi dinar will not revalue because US troops have left. The CBI sets the exchange rate, not the US military. The CBI has not changed its position, has issued two formal denials of rate change rumours in the past month, and has made clear that any future currency restructuring will follow a lengthy legal and technical process. The parallel market is pricing in uncertainty, not an imminent windfall.
The forums will find ways to explain why it did not happen, and will set a new date. They always do. The question worth asking, as always, is not whether this moment is historically significant for Iraq. It is. The question is whether anything about it changes the investment thesis for a shoebox of banknotes sitting outside Iraq.
It does not.
This article does not constitute financial or investment advice. If you are holding Iraqi dinars and considering your options, consult a licensed, regulated financial advisor, not an online forum.
For more information on the Iraqi dinar, check out IBN's Dinar Page here: https://www.iraq-businessnews.com/the-dinar-page/
See also:
- Official Holiday Declared for Iraq's Sovereignty Days
- CBI Rebuffs Speculation Over Foreign Currency Reserves
- Top 10 Dinar Articles from August
- What a New Iraqi PM Means for Your Dinars
- "Deleting the Zeros": What Iraq Actually Said, and What It Means for Your Investment
- You Bought Iraqi Dinars. Now What?



No comments yet.